Here is the part most people miss about market seasonality: A massive headline number is not a trading strategy.
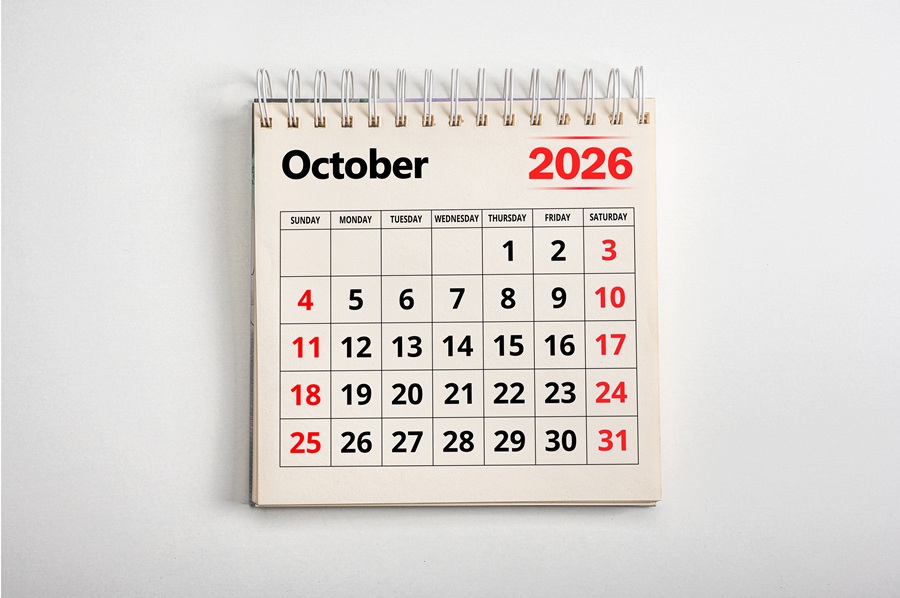
China's National Day Golden Week runs from Thursday 1 October to Wednesday 7 October 2026. The final 2026 travel numbers are not known yet, but the scale of the event is clear from last year.
During the combined 8-day National Day and Mid-Autumn holiday in 2025, China recorded 888 million domestic tourist trips and RMB809.006 billion in domestic tourism spending, according to the Ministry of Culture and Tourism. That is the benchmark. Not a forecast.
The 2026 calendar adds another wrinkle. Mid-Autumn runs from Friday 25 September to Sunday 27 September, as covered in our analysis of Mid-Autumn consumer stock catalysts and Asian session trading conditions. Then there are only 3 regular working days before Golden Week begins.
Someone taking annual leave from 28 to 30 September could therefore stitch the 2 holidays into a continuous 13-day break.
That is not just creative calendar maths. The State Council's official 2026 holiday notice encourages employers and individuals to combine paid annual leave with public holidays where appropriate to create longer breaks and support staggered travel. Travel volume could be substantial.
What is not guaranteed is where that spending lands, how profitable it is, or whether the final numbers beat expectations already reflected in asset prices. That is where an if/then scenario matrix becomes useful.
The Golden Week if/then matrix
This is not about deciding the trade before the data arrives. It is about identifying which developments are most relevant to which markets.
| Market trigger | Primary market proxy | 9 September 2026 reference | What it could mean |
|---|---|---|---|
| Travel bookings and pricing strengthen | Trip.com (9961.HK) and Cathay Pacific (0293.HK) | Trip.com around HK$316. Cathay around HK$14.45 | Stronger travel demand or pricing could improve sentiment towards travel-linked names |
| Macau gaming activity strengthens | Sands China (1928.HK) and Wynn Macau (1128.HK) | Sands around HK$13.79. Wynn around HK$5.61 | Stronger gaming revenue or visitation could refocus attention on casino operators |
| Trip numbers rise but spending per traveller disappoints | FTSE China A50 Index | Around 14,701 | Strong volume with weaker expenditure could reinforce concerns about household caution |
There is deliberately no long or short column. A positive economic number does not guarantee a positive share-price reaction. The surprise relative to expectations matters. So do margins, valuation and whatever the market has already priced in.
Setup 1: travel and mobility
If travel demand holds up, hundreds of millions of journeys during Golden Week are nothing unusual in China. The more interesting question is what kind of travel takes place and how much consumers spend while doing it.
Longer trips, stronger airline pricing and higher accommodation demand tell a different commercial story from packed trains and heavily discounted travel packages. That puts 2 listed travel names in focus for the Asia-Pacific market outlook.
1. Trip.com Group (9961.HK / TCOM)
Trip.com sits directly in the booking chain through accommodation reservations, transportation ticketing, packaged tours and corporate travel services.
The latest reported results
Trip.com's latest reported financial results are still Q1 2026. The company reported total net revenue of RMB16.2 billion, up 17% year on year (YoY), primarily driven by resilient travel demand. Accommodation reservation revenue rose 17% YoY and transportation ticketing revenue rose 12%.
That reporting lag is about to change. Trip.com has scheduled its Q2 and first-half 2026 results for Tuesday 15 September 2026 US time, after the US market close. The associated conference call is scheduled for 16 September Hong Kong time. That makes earnings a separate corporate catalyst before Golden Week. If the company changes that reporting timetable, the publication should be updated accordingly.
The technical picture
| Metric | Chart reference |
|---|---|
| 9 September 2026 close | Around HK$316 |
| Recent September upper reference | Around HK$353 |
| Recent September lower reference | Around HK$315 |
| Round-number reference | HK$300 |
What to watch
If Trip.com's scheduled Q2 results and later holiday booking data point in the same direction, the market may have a clearer travel narrative to work with. If they diverge, things get more interesting. A busy Golden Week does not automatically offset weaker margins, softer guidance or expectations that were already high. Millions of suitcases are one thing. The income statement is another.
2. Cathay Pacific Airways (0293.HK)
Cathay adds a different part of the travel equation. Rather than earning booking commissions, the airline is exposed to passenger numbers, fares, capacity, fuel and operating costs.
Cathay's official 2026 interim report showed HK$68.061 billion in group revenue for the first half and HK$6.243 billion in attributable profit. Passenger-services revenue rose 27.2% YoY, while cargo-services revenue increased 23%.
| Metric | Chart reference |
|---|---|
| 9 September 2026 close | Around HK$14.45 |
| Recent September upper reference | Around HK$14.65 |
| Recent September lower reference | Around HK$13.42 |
What to watch
For Cathay, passenger volume is only part of the story. Pricing, capacity and costs matter too. A crowded airport can make a fantastic photograph. It cannot tell you the airline's margin.
Trade Asia-Pacific Share CFDs
Access competitive leverage, tight spreads, and multi-asset coverage across major regional exchanges.
Setup 2: Macau gaming
If Golden Week reaches the casino floor, Macau gives the Golden Week story another layer. Gaming revenue can provide a more direct read on discretionary leisure spending than broad tourism numbers alone.
The latest official data gives the holiday an interesting starting point. Macau's Gaming Inspection and Coordination Bureau (DICJ) reported MOP21.891 billion in gross gaming revenue (GGR) for August 2026, down 1.2% YoY. For the first 8 months of 2026, accumulated GGR stood at MOP169.053 billion, up 3.7% from the same period in 2025. That is the official baseline.
High-frequency numbers are different. Broker channel checks may estimate daily activity between DICJ releases, but those estimates should not be presented as official gaming statistics.
3. Sands China (1928.HK)
Sands China operates major integrated resorts across Macau, including properties on the Cotai Strip.
| Metric | Chart reference |
|---|---|
| 9 September 2026 close | Around HK$13.79 |
| Recent September upper reference | Around HK$14.30 |
| Recent September lower reference | Around HK$13.52 |
A move outside that recent range may attract attention if it arrives alongside new evidence on visitation or gaming activity. But the share-price move alone does not establish the cause.
4. Wynn Macau (1128.HK)
Wynn Macau provides another listed exposure to the same broad gaming theme.
| Metric | Chart reference |
|---|---|
| 9 September 2026 close | Around HK$5.61 |
| Recent September upper reference | Around HK$5.80 |
| Recent September lower reference | Around HK$5.51 |
What to watch
It is tempting to nominate one daily gaming-revenue number and call everything above it bullish. Markets are rarely that accommodating. Official DICJ GGR, visitor arrivals, hotel occupancy, customer mix and analyst expectations can all shape the eventual reaction. The surprise matters as much as the headline.
Setup 3: the macro disconnect
If everybody travels but nobody splurges, this is where the Golden Week headline can become deceptive.
Suppose domestic trip numbers are strong. Now suppose spending per traveller is less impressive. Both can be true. In 2025, the combined National Day and Mid-Autumn period produced 888 million domestic trips and RMB809.006 billion in domestic tourism expenditure.
For 2026, trip volume and total expenditure will need to be considered together. Strong travel accompanied by weaker expenditure per traveller could suggest households remain willing to travel but are being more selective about discretionary spending. That tells a very different story from travel volumes rising alongside stronger overall expenditure.
5. FTSE China A50 Index
The FTSE China A50 Index tracks the 50 largest eligible A-share companies listed on the Shanghai and Shenzhen exchanges. For traders, it offers a broad reference point for large mainland equities rather than a pure consumer-spending index.
| Metric | Chart reference |
|---|---|
| 9 September 2026 close | Around 14,701 |
| Recent lower reference zone | Around 14,575 to 14,600 |
| Recent upper reference zone | Around 14,800 to 14,900 |
What to watch
If post-holiday data shows strong travel volumes but softer spending, broader China equity markets may provide one read on whether investors interpret the numbers as consumer resilience or continued household caution.
There is one important complication: mainland markets are closed while much of the holiday activity is actually taking place. As detailed in our guide on China stock market hours and holiday schedules, the official 2026 National Day holiday runs from 1 to 7 October, with mainland markets reopening after the break. The State Council notice also identifies 20 September and 10 October as adjusted working days.
Some of the domestic equity market's price discovery therefore comes later. The tourists move first. The mainland market gets its turn afterwards.
What could break the matrix?
The point of an if/then framework is not to predict the answer. It is to recognise when reality stops following the original story. Three risks stand out:
1. Stock Connect pauses
HKEX's official 2026 calendar confirms that Northbound and Southbound Stock Connect trading is closed on the opening Golden Week dates, including 1, 2, 5 and 6 October. That changes the normal cross-border participation mix. It does not automatically mean Hong Kong liquidity in trading disappears or volatility rises. Other investors can still trade Hong Kong-listed securities when the local market is open. The composition of the flow is simply different.
2. Expectations can move before tourists do
Golden Week is not a surprise event. The date is known well in advance. Bookings arrive before the holiday. Earnings expectations adjust before the holiday. Share prices can move before the holiday. By the time a strong headline lands, part of the story may already be reflected in price. In technical trading, this can result in crowded trade conditions where good news meets a flat stock. Markets do enjoy ruining a perfectly good narrative.
3. Volume is not profitability
This is the important one. A packed airport does not automatically mean stronger airline margins. A full hotel does not tell you the commission retained by an online travel platform. A crowded Macau does not tell you casino hold, customer mix or promotional costs. And even another enormous national travel number would tell only part of the story. The spending mix matters. So does the cost of capturing it.
Headline travel numbers describe activity, not profitability. For traders, the key is evaluating how reality measures up against analyst expectations already priced into asset valuations.
Trade global markets with GO Markets
Explore forex, indices, commodities and share CFDs with competitive spreads and expert support.

The information provided is of general nature only and does not take into account your personal objectives, financial situations or needs. Before acting on any information provided, you should consider whether the information is suitable for you and your personal circumstances and if necessary, seek appropriate professional advice. All opinions, conclusions, forecasts or recommendations are reasonably held at the time of compilation but are subject to change without notice. Past performance is not an indication of future performance. Go Markets Pty Ltd, ABN 85 081 864 039, AFSL 254963 is a CFD issuer, and trading carries significant risks and is not suitable for everyone. You do not own or have any interest in the rights to the underlying assets. You should consider the appropriateness by reviewing our TMD, FSG, PDS and other CFD legal documents to ensure you understand the risks before you invest in CFDs. These documents are available here.
Any references to Australian or international shares, sectors, indices, ETFs, crypto-related stocks or other instruments are provided for market commentary and watchlist purposes only and do not constitute a recommendation, offer or solicitation to buy, sell or hold any financial product or adopt any investment strategy. International markets may involve additional risks, including currency fluctuations, regulatory differences, market structure differences, reduced liquidity and higher volatility. Company-specific, sector-specific and macroeconomic risks may also affect performance.
Commentary on geopolitical developments, economic data, central bank decisions, earnings, policy changes and other global or financial market events is based on information available at the time of publication and may change without notice. Such events can lead to sudden market moves, price gaps, reduced liquidity, wider spreads and increased volatility, particularly in leveraged products such as CFDs. Forward-looking statements, expectations and scenario analysis are inherently uncertain and should not be relied on as guarantees of future market behaviour or outcomes.